Executive Summary
Zomato remained a core business of Eternal in FY26 and continued to combine customer growth, higher order volumes, stronger monetisation and improving profitability. Food delivery operations were present across 900+ cities as of March 2026.
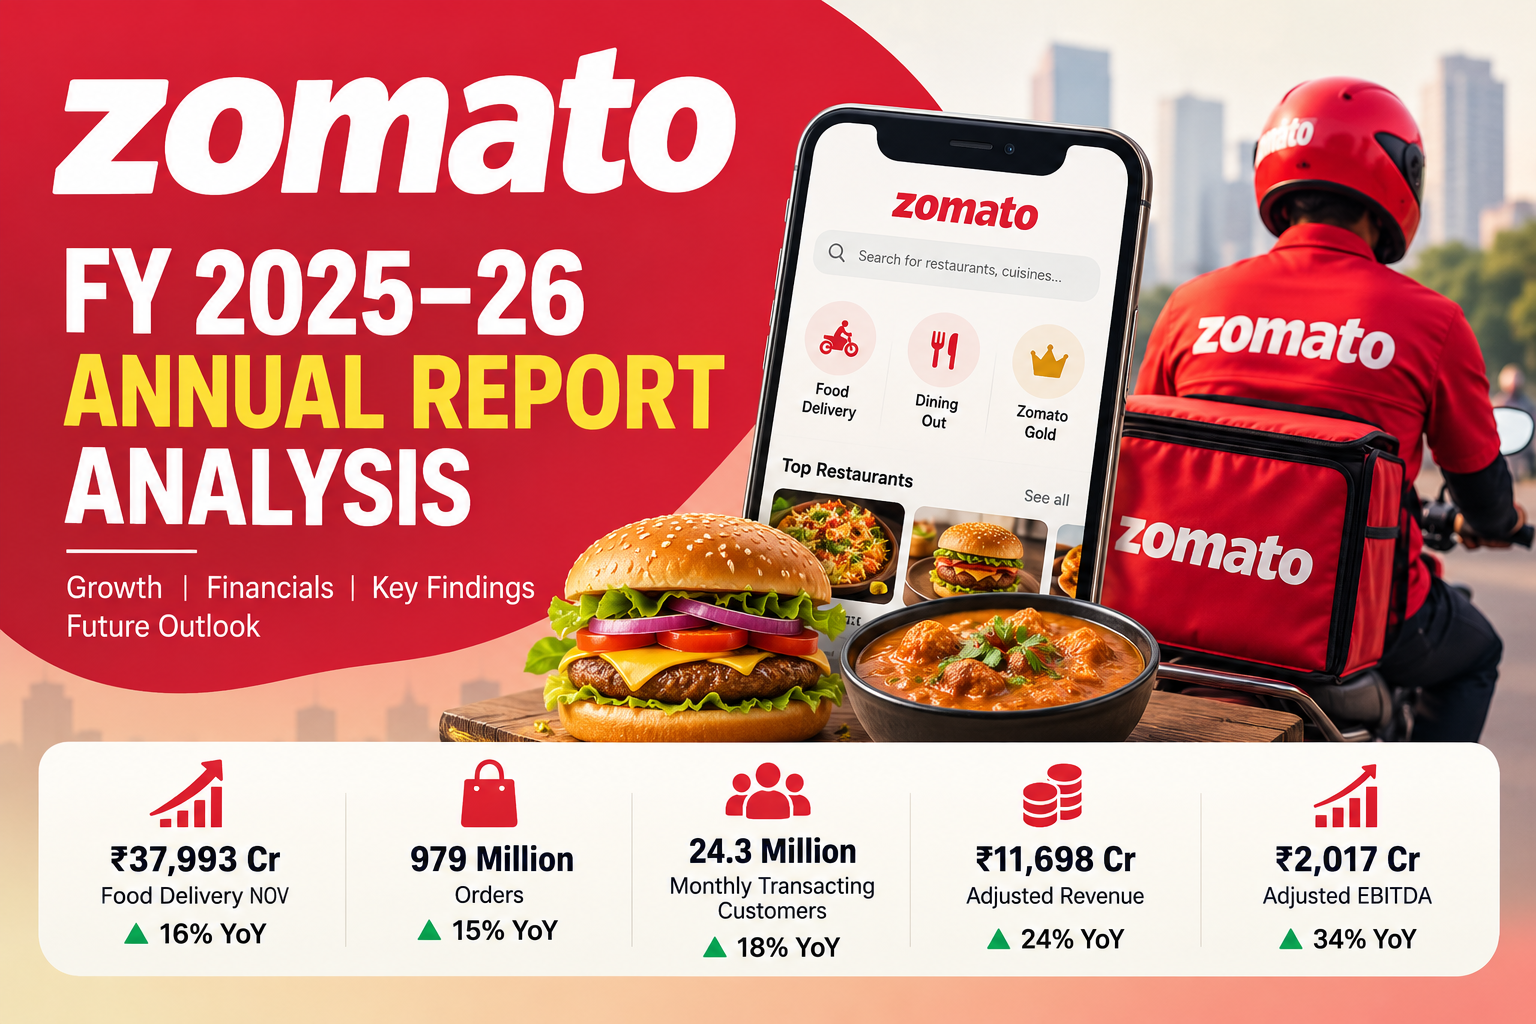
The central FY26 story is profitable growth: monthly transacting customers increased 18%, orders increased 15%, food-delivery NOV increased 16%, while Adjusted EBITDA grew 34% and the Adjusted EBITDA margin expanded to 5.3%.
FY26 Operating and Financial Snapshot
Metric | FY26 / Finding |
Food Delivery NOV | ₹37,993 crore; +16% YoY |
Orders | 979 million; +15% YoY |
Net AOV | ₹388; +1% YoY |
Monthly transacting customers | 24.3 million; +18% YoY |
Monthly active delivery partners | 552,000; +17% YoY |
Monthly active restaurant partners | 330,000; +11% YoY |
Adjusted Revenue | ₹11,698 crore; +24% YoY |
Adjusted EBITDA | ₹2,017 crore; +34% YoY |
Adjusted EBITDA margin | 5.3%, up from 4.6% |
Active Zomato Gold members | 24.2 million |
Business Model
Zomato operates a B2C technology platform connecting end customers, restaurant partners and independent delivery partners. The platform supports restaurant discovery, food ordering and delivery at scale.
Customer and Order Growth
FY26 order growth was driven primarily by expansion in the customer base and transaction frequency rather than a material increase in average order value. Monthly transacting customers reached 24.3 million, while orders reached 979 million.
The company also focused on affordability and customer activation. Zomato Gold remained an important membership layer, with 24.2 million active members at March 2026. The report highlights the reduction of the minimum order value for free delivery under Gold from ₹199 to ₹99, subject to applicable terms.
Revenue and Monetisation
Food-delivery Adjusted Revenue increased 24% to ₹11,698 crore, faster than NOV growth of 16%. Adjusted Revenue as a percentage of NOV improved from 28.7% to 30.8%. The report attributes the improvement mainly to higher revenue per order, increased platform fees and stronger advertising monetisation.
Profitability
Food-delivery Adjusted EBITDA increased from ₹1,505 crore in FY25 to ₹2,017 crore in FY26. Margin expanded from 4.6% to 5.3%. The company attributes the improvement to higher revenue per order and cost efficiencies, despite a shift toward lower-value orders.
Product and Platform Initiatives
Zomato Gold: membership benefits including free delivery and exclusive offers, subject to terms.
Healthy Mode: an AI-powered experience focused on healthier food discovery and nutritional information.
Chef's Table: curated tasting experiences designed to help customers sample signature dishes.
Food rescue, Food on Train, Zomato for Enterprise, scheduled orders and group ordering.
Friends' recommendations and other discovery-oriented product features.
Strategic Outlook
Eternal expects food-delivery NOV growth to move toward its long-term expectation of 20%+ as market-share gains, affordability initiatives and greater selection support demand.
Key Findings
1. Customer expansion is a stronger growth driver than average order value expansion.
2. Food delivery is the strongest profitability contributor among the major businesses.
3. Revenue monetisation is improving faster than NOV.
4. Zomato Gold creates a large engagement and retention ecosystem.
5. The business is increasingly positioned as a mature, profitable core business that can support investment in newer businesses.
Conclusion
FY26 was a year of profitable growth for Zomato food delivery. The combination of customer growth, order growth, stronger monetisation and margin expansion strengthens the business's role as an important earnings engine within Eternal.